Ohio InsuranceAppraiser (844) 537-1427

Independent claim appraisal · All 88 counties

Ohio Insurance Appraiser: a second, independent number for your property claim

When the insurer accepts the claim but the check won’t cover the repair, Ohio Insurance Appraiser builds its own line-item valuation and takes it through the appraisal clause in your policy.

  • Your appointed appraiser
  • Ohio pricing, ZIP by ZIP
  • Homes, HOAs & businesses

Get a free claim review

Two minutes. A real person calls back.

Scope from scratchWe measure and photograph it ourselves.
Defensible numbersPriced to hold up in front of an umpire.
Fees in writingBefore any work starts.
Straight answersIf appraisal isn’t right, we say so.

Why owners call us

Covered isn’t the same as paid in full

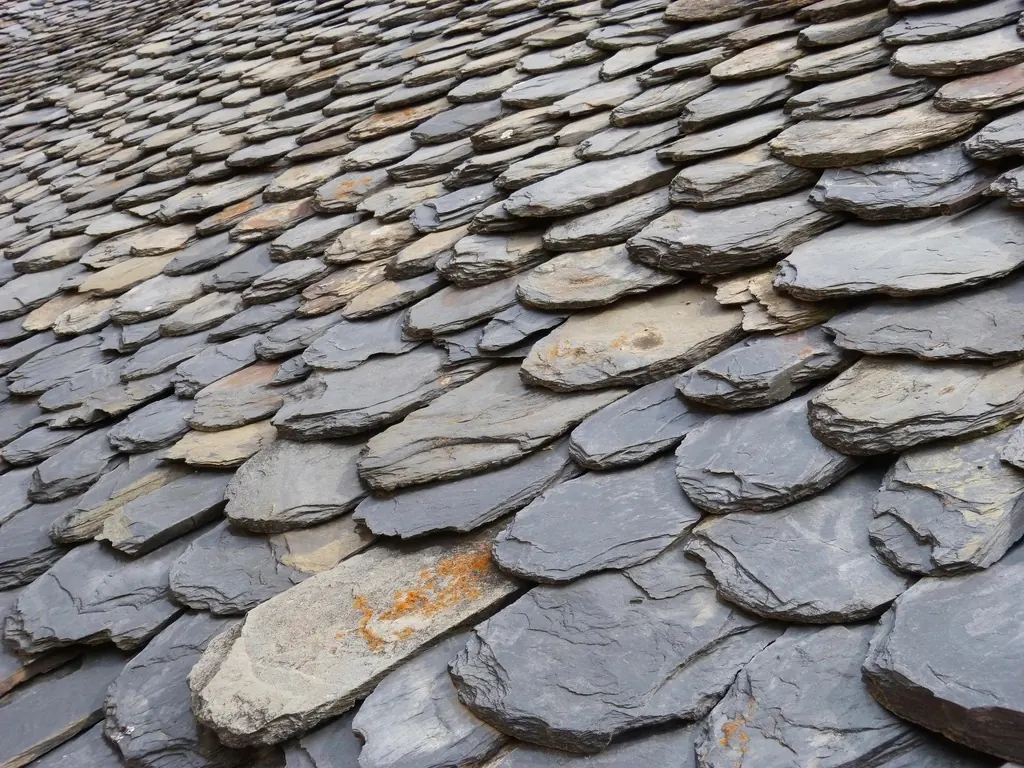
Most underpaid Ohio claims aren’t denied — they’re short. A slate roof priced as asphalt. A finished basement scoped as bare block. Ice-and-water barrier left off a snowbelt roof. Ohio Insurance Appraiser exists for that gap between “approved” and “enough to fix it.”

As an Ohio Insurance Appraiser, our job is narrow on purpose: work out what the loss really costs, write it up so every line can be checked, and see it through the appraisal clause if the insurer won’t move. We don’t sell roofs, we don’t take over your claim and we don’t practice law.

  • Independent inspection and measurements — never an edited copy of the insurer’s estimate.
  • Line items priced for your part of Ohio, with code items and overhead and profit treated the way your policy reads.
  • Honest triage: if a denial needs an attorney, you’ll hear it on the first call.
How the firm works
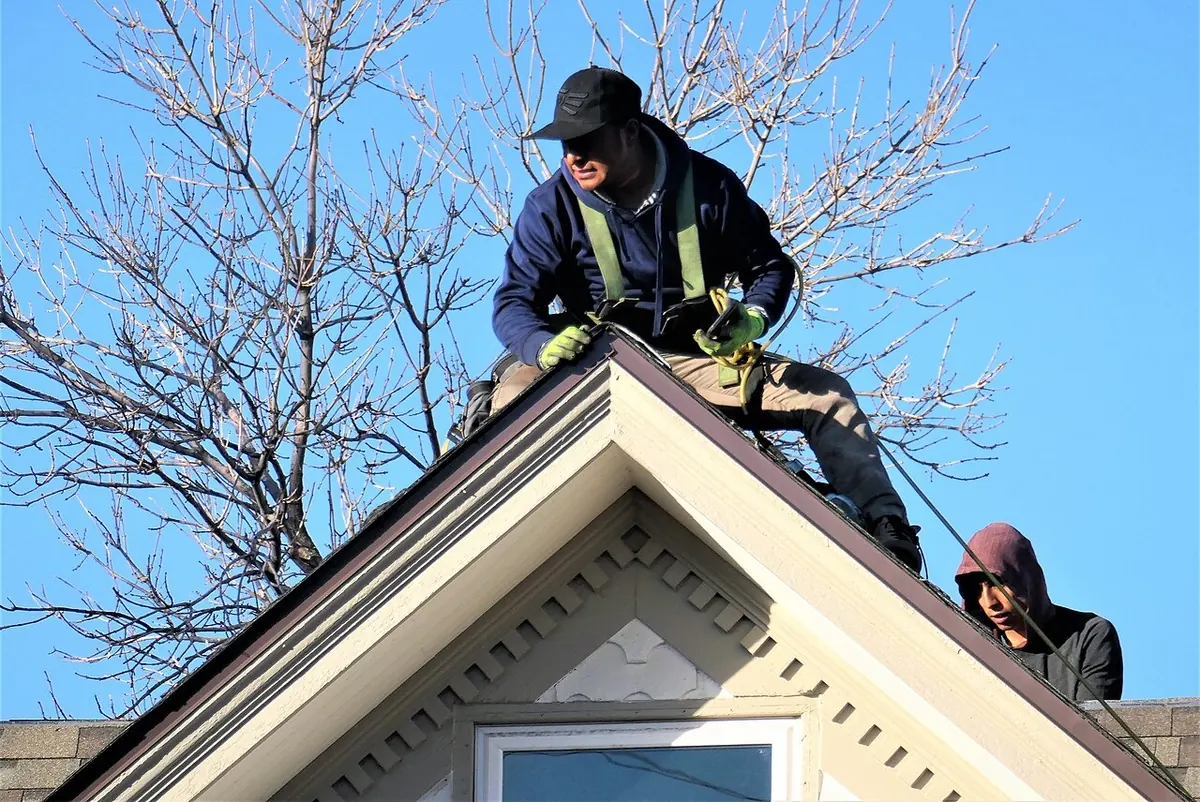
Roofers in safety harnesses working on the peak of a house roof
Inspected, measured, priced. Every Ohio Insurance Appraiser estimate starts on site.
88Ohio counties served
5Weather regions, five claim patterns
11Appraisal & estimating services
7Free claim tools

Lake Erie to the Ohio River

Five Ohio regions, five kinds of claims

Snowbelt ice dams in Ashtabula, hail in Franklin County, tornadoes in the Miami Valley, ice storms in the hills. An Ohio Insurance Appraiser has to know how each region’s weather shows up on a roof — and on an estimate.

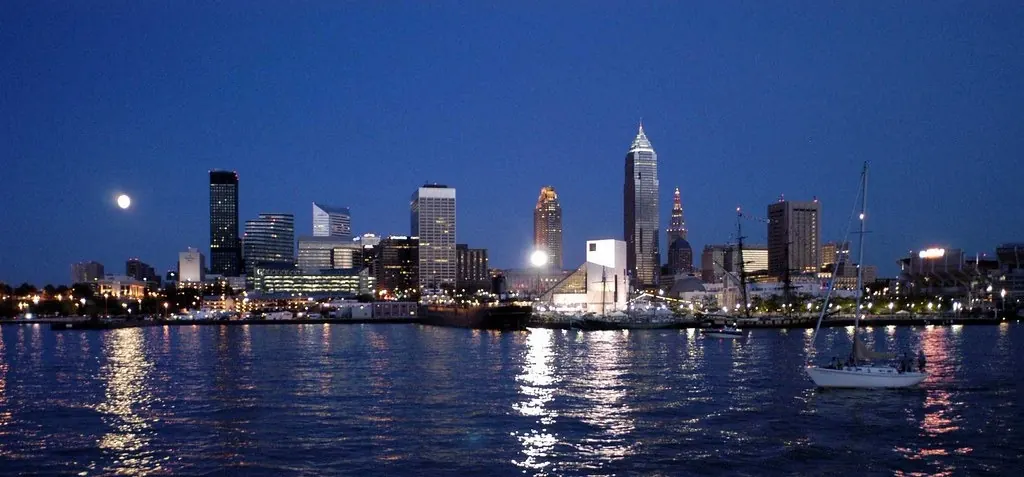
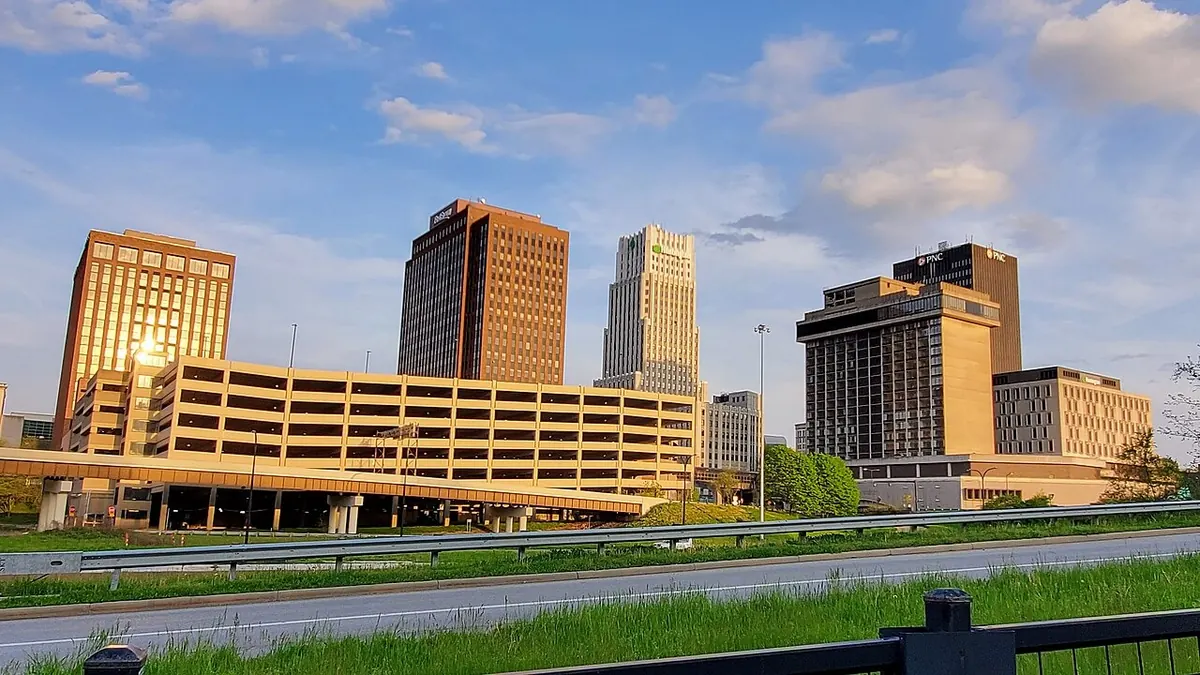
Cleveland · Akron · Canton · Youngstown

Northeast Ohio

Lake-effect snow piles up in the snowbelt east of Cleveland, which means ice dams, snow-load damage and burst pipes in century-old homes. Spring and summer bring hail and straight-line wind across Summit, Stark and Mahoning counties.

  • Lake-effect snow
  • Ice dams
  • Hail
  • Old slate roofs

Toledo · Sandusky · Lima

Northwest Ohio

Flat farmland gives storms a clear run. Tornadoes, derecho winds and hail cross Lucas, Wood, Erie and Allen counties, while Lake Erie adds wind-driven rain and lakeshore exposure.

  • Tornadoes
  • Straight-line wind
  • Hail
  • Farm buildings

Columbus and suburbs

Central Ohio

Franklin County’s fast-growing suburbs mean big subdivisions of similar homes — and big hail and wind events that hit thousands of roofs at once, as the 2012 derecho showed.

  • Derechos
  • Hail
  • Wind
  • Basement water

Cincinnati · Dayton · Xenia

Southwest Ohio

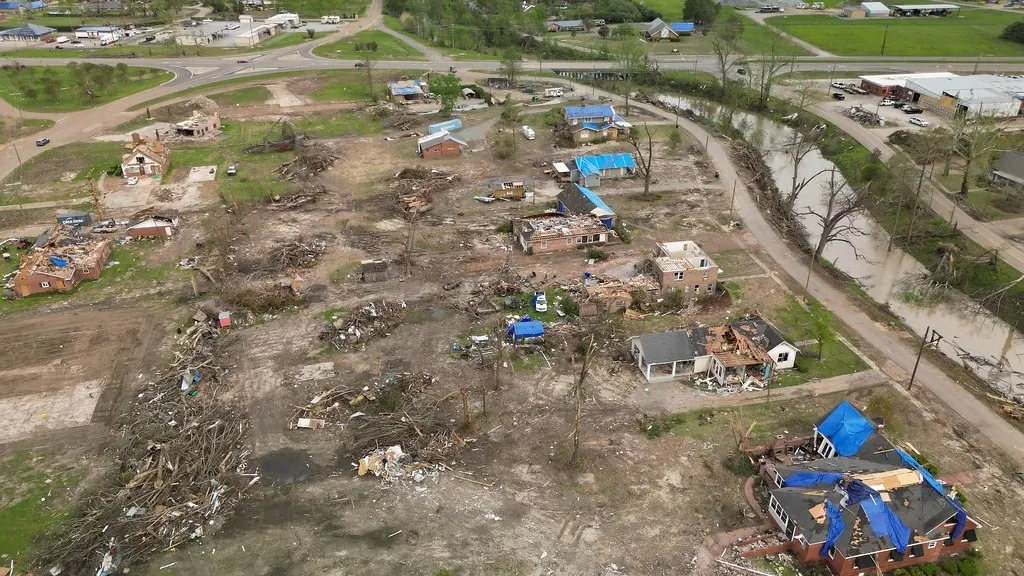
The Miami Valley sits in one of Ohio’s busiest tornado corridors, from Xenia in 1974 to the Memorial Day 2019 outbreak. Cincinnati’s hillside homes add tree, wind and water problems.

  • Tornadoes
  • Hail
  • Hillside water
  • Tree damage

Zanesville · Athens · Marietta

Southeast Ohio

Appalachian hills, river towns and older frame and brick homes. Ice storms, fallen trees and basement water are the claims that come up most along the Muskingum and the Ohio River.

  • Ice storms
  • Fallen trees
  • River-town basements
  • Older homes

The process

How Ohio Insurance Appraiser moves a stuck claim

The appraisal clause turns an open-ended argument into a defined process with a binding result on the amount of loss.

  1. 1

    Free claim review

    We read the policy, the insurer’s estimate and your photos, then tell you whether appraisal is the right tool.

  2. 2

    Independent scope

    Our own inspection, measurements and a line-item estimate priced for your part of Ohio.

  3. 3

    Written demand

    Appraisal is demanded in writing and we’re named as your appraiser inside the policy’s window.

  4. 4

    Panel work

    Line-by-line work with the insurer’s appraiser. Most of the gap usually closes here.

  5. 5

    Signed award

    Anything left goes to the umpire. Two signatures set the amount of loss.

Read the full appraisal timeline

Storm memory

Ohio storms that shaped how claims are handled

Ohio’s worst weather days still echo in policy language — percentage wind deductibles, flood exclusions and backup sublimits. An Ohio Insurance Appraiser reads every claim against that history.

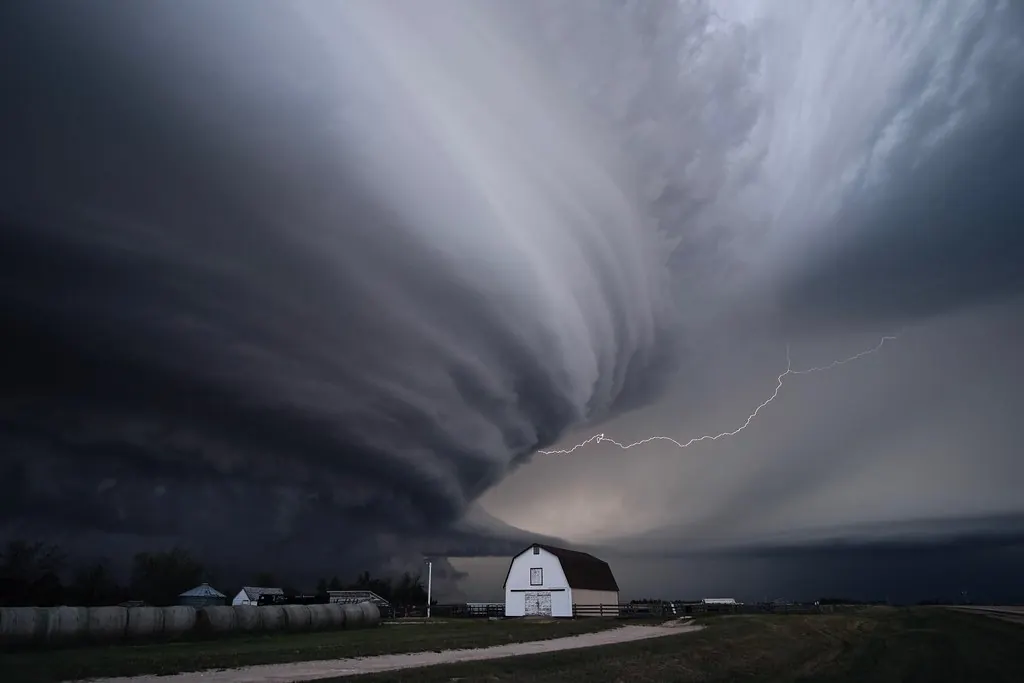
Supercell thunderstorm with a lightning bolt over a barn and open farmland
  1. 1913

    The Great Flood

    Rivers across the state overtopped their banks in March 1913, devastating Dayton and swamping Columbus and Zanesville. Flood is still excluded from homeowners policies today.

  2. 1924

    Lorain–Sandusky tornado

    The deadliest tornado in Ohio history tore through Sandusky and Lorain on June 28, 1924.

  3. 1974

    Xenia

    An F5 tornado in the April 3, 1974 Super Outbreak cut through Xenia, one of the most destructive tornadoes the state has recorded.

  4. 1978

    The Great Blizzard

    January 1978 brought hurricane-force winds and drifting snow statewide — the benchmark for Ohio winter storms.

  5. 2008

    Ike’s remnants

    On September 14, 2008, the remains of Hurricane Ike crossed Ohio with hurricane-force gusts, leaving roughly two million customers without power and roofs damaged statewide.

  6. 2012

    The derecho

    On June 29, 2012, a derecho swept Columbus and central and southern Ohio, knocking out power to about a million customers.

  7. 2019

    Memorial Day outbreak

    Tornadoes, including an EF4, hit Trotwood, Harrison Township, Brookville and Beavercreek around Dayton.

Choosing help

Appraiser, public adjuster or attorney?

Each solves a different problem. Ohio Insurance Appraiser will point you elsewhere when appraisal isn’t the right tool.

Ohio Insurance Appraiser

Values the amount of loss

  • Best when coverage is accepted and the number is disputed
  • Result: an award signed by two of three
  • Doesn’t decide coverage

Public adjuster

Handles and negotiates the claim

  • Best early, from first notice
  • Result: a negotiated settlement
  • Licensed by the Ohio Department of Insurance

Attorney

Legal disputes and lawsuits

  • Best for denials, bad-faith questions and deadlines
  • Result: settlement or judgment
  • Argues coverage in court

Q&A

Questions people ask an Ohio Insurance Appraiser

Short, straight answers about appraisal, costs and timing.

What does an Ohio Insurance Appraiser do?

We put an independent value on property damage when you and your insurer agree the loss is covered but disagree on what it costs. As your named appraiser we inspect, build a line-item estimate, work through it with the insurer’s appraiser and, if needed, present unresolved items to an umpire.

How is an appraiser different from a public adjuster?

A public adjuster handles and negotiates the whole claim. An appraiser works inside the policy’s appraisal clause on one question: the amount of loss. We don’t negotiate claims outside appraisal and we don’t give legal advice.

Is the appraisal award binding in Ohio?

Under the standard appraisal clause, a written award signed by any two of the three panel members sets the amount of loss. It doesn’t decide coverage questions, so read your policy and get legal advice on anything beyond the dollar figure.

What does appraisal cost?

Each side usually pays its own appraiser and half of the umpire. We give you our fee in writing before any work starts, and the first conversation is free.

How long does an Ohio appraisal take?

Many finish within a few months of the demand, depending on how fast the panel forms, how big the loss is and whether an umpire is needed. Policy deadlines, including suit limitations, keep running, so keep an eye on the calendar.

Do you cover my county?

Yes. We work in all 88 Ohio counties, with frequent work around Columbus, Cleveland, Cincinnati, Toledo, Akron, Dayton and the Mahoning Valley.

Check the numbers before you sign off on them

A short review now can keep you from accepting a settlement that won’t pay for the repair.

Start with a conversation

Talk to an Ohio Insurance Appraiser about your claim

Tell us what happened and what the insurer offered. We’ll review it and tell you whether appraisal is worth pursuing — no pressure.

Tell us about the claim

Free review · no obligation · reply within one business day

Call Free review